Georgian brick town houses with green and red front doors under fanlights

Capital markets

Investor money and lending arranged for private companies with plans to grow, acquire, or reshape who owns them.

Raising capital, carefully

The interest rate or the valuation is only part of what capital costs. Covenants, investor rights, reporting duties, and repayment dates decide how freely a company can move for years, so they deserve equal scrutiny.

Our first conversation is about purpose. Opening a new location, buying a competitor, paying out a retiring partner, or replacing an old loan each points to different sources of money, and the balance of borrowing and investment depends on how dependable your profits are and how much influence you wish to retain.

Next we put the company’s argument on paper and take it to lenders and investors who genuinely suit you, so they compete and the terms improve. Every proposal is set out clearly, alongside our recommendation.

Clients include family firms welcoming their first outside investor, growing businesses paying for expansion, and owners financing an acquisition or a partner buyout.
An adviser talking an older couple through figures on a laptop

Who we work with

Private companies with a clear purpose for new capital.

Expanding companies

You have a plan for growth and need capital that supports it without unnecessary strain.

Acquirers

There is a company you intend to buy, and the money needs to be secured before you put in a bid.

Owners seeking liquidity

You hope to turn part of your stake into cash, or pay out a co-owner, without losing control.

Financing services

Every source of money carries different costs and conditions. Once you have chosen, we run the process that secures it.

Two advisers in suits reviewing papers at a kitchen table

Minority equity

Outside investors take a smaller share and their money goes straight into the business, while control stays with you. We bargain over the valuation, the seats they get on the board, and the protections they ask for.

Suited to: expanding firms that want a backer rather than a new boss.

A speaker presenting to a seated audience in a glass-walled conference room

Majority equity

A buyout fund acquires control, and founders and senior managers usually roll a sizable stake into the new company. We line the funds up against each other on price, plans, and their record with management teams.

Suited to: founders ready to step back from control in return for a larger sale.

A hand marking figures on printed financial documents

Bank loans

Term debt and revolving facilities from community, regional, and national banks, typically the cheapest money a company can raise. Bringing several lenders in at once keeps rates honest and covenants sensible.

Suited to: profitable firms with dependable cash generation.

A calculator resting on a printed financial statement

Private credit

Loans from specialist debt funds that can go further and decide faster than most banks. Every fee is laid out up front, so you can judge whether the flexibility is worth its higher price.

Suited to: businesses that need more than their bank is willing to extend.

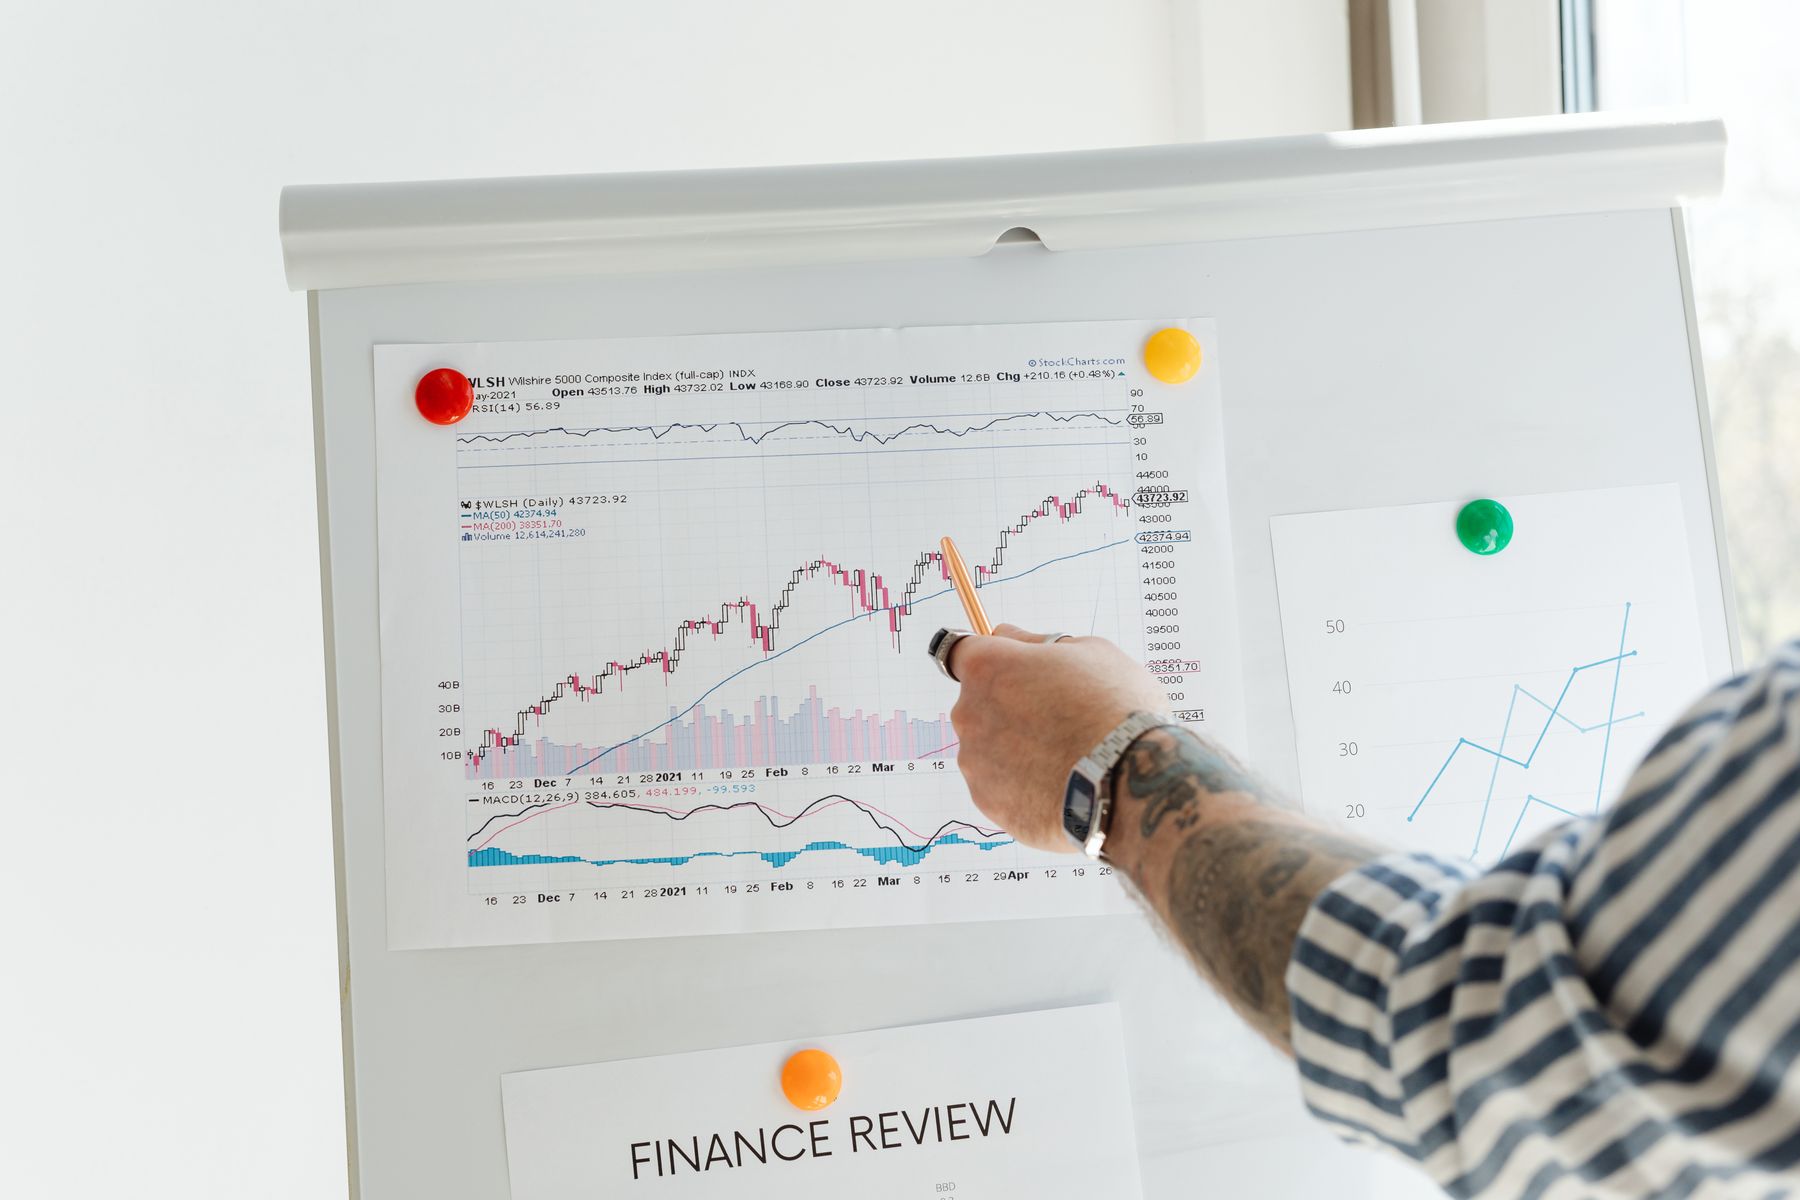
A hand pointing at a chart on a whiteboard

Acquisition financing

Funding confirmed before you make an offer, so the seller can take the bid at face value. Loan documents and the purchase agreement move forward together from the first draft.

Suited to: acquirers with one target in view or several in mind.

A hand working a calculator over printed plans

Refinancing

Swapping out borrowing that has grown expensive, restrictive, or close to its due date for terms that match the company as it stands now.

Suited to: businesses whose borrowing no longer matches their size.

The path to funding

Expect three to six months from first meeting to funded. The stages, and where your input comes in, are below.

  1. Defining the needWeeks 1 to 3

    We settle why the company needs money, how much, and the split between loans and investor capital that your profits can sustain.

    From you: your plans, recent figures, and your view on sharing control.

  2. Building the materialsWeeks 3 to 8

    We prepare projections and a presentation for prospective lenders or investors,, with the difficult questions already addressed.

    From you: time with your bookkeeper or finance lead.

  3. Going to marketMonths 2 to 4

    Hand-picked banks, funds, or investors are approached under confidentiality. Meetings are booked and follow-up handled, with one shared deadline for everyone.

    From you: a few presentations and the occasional site tour.

  4. Comparing termsMonths 3 to 5

    Proposals are set out on price, structure, and control, and the leading ones are asked to sharpen their terms.

    From you: a decision on how much flexibility is worth paying for.

  5. Closing the raiseMonths 4 to 6

    Final checks and legal paperwork, coordinated with your attorney and accountant, so the money arrives on the agreed date.

    From you: prompt replies and sign-off on the finished documents.

How we work

What every company raising capital can count on.

Clear advice

A recommendation on the right type of capital, with our reasoning.

Competing offers

Several lenders or investors bidding for your business.

Side-by-side terms

Every proposal set out clearly on cost and conditions.

To the finish

We stay with you until the funds are received.

Questions about capital

Stone steps leading up to a front door, lined with potted plants
Debt or equity: which suits us?

A loan leaves ownership untouched but has to be paid back, with conditions along the way. Investor money carries no repayments, though it means sharing ownership and a measure of control. We run the numbers on both for your company.

How large a loan can we get?

Lenders size a loan mostly on profits and cash generation, then weigh the quality of your customers and any collateral. We settle on a realistic figure before a single lender is contacted.

Will an investor take control?

Only if you pick a majority deal. A minority investor holds a smaller share and usually wants a board seat and a say on major decisions.

Why consider private credit?

Specialist lenders will often stretch further, bend more, and decide sooner than a bank. They charge for it, so it is worth doing only when those advantages unlock something valuable.

How long does it take?

Roughly a quarter for a straightforward bank loan, and between four and six months for equity or more layered financing.

What will lenders and investors want to see?

Recent years of accounts, a forecast you can defend, background on customers and leadership, and a plain explanation of where the money goes.

Should our current bank be involved?

Usually, yes. A bank that already knows you tends to sharpen its offer once it sees credible competition.

How are you paid?

A small monthly fee during preparation and a completion fee once the funds land, both agreed in writing on day one.

A row of red-brick town houses with bay windows and gabled roofs

Write to Pemberton Row

Send a short note on the company and the step you have in mind. One of our senior bankers will answer you directly, and your note stays strictly between us.

info@pemberton-row.com
Email us